
AI-native financial research
agent by AlephEdge
General intelligence meets financial expertise: understand research intent, use specialist tools, and move from data analysis to strategy validation.
General intelligence.Financial expertise.
Ordinal brings general-purpose reasoning and analysis together with financial research methods and specialist tools, from understanding a complex question to testing an investment idea.
Frame the question
Turns a vague idea into testable hypotheses, with clear data, periods and criteria.
Analyse the data
Reads your factor and result files and points out anomalies, gaps and what is worth a closer look.
Build a research plan
Lays out the steps and control experiments so every conclusion is backed up.
Do the work
Calls evaluation, synthesis and backtesting with your parameters, then explains the results.
Research intent, put into action
- Built-in tool plugins
- 50+
- Search, analysis, execution and delivery
- Professional Skills
- 10+
- Specialist methods and research workflows
- Quantitative research tools
- 16
- Data, factors, signals and backtests
- Core research modules
- 4
- From the factor library to strategy validation
Open to extend. Built to evolve.
An open platform for research
Bring your own Skills and plugins
- 67%
xbench DeepSearch
Powerful General CapabilitiesAccuracy · October 2026
- 90%
Financial Audit Bench
Accurate Financial JudgmentSubitem pass rate · October 2026
Rapid development
Continuously evolving capabilities
Four connected research modules
From factor assets to strategy validation, each stage connects to the next.
Factor library
A large set of built-in classic factors, plus your own; pick a universe and dates and generate factor values in one click.
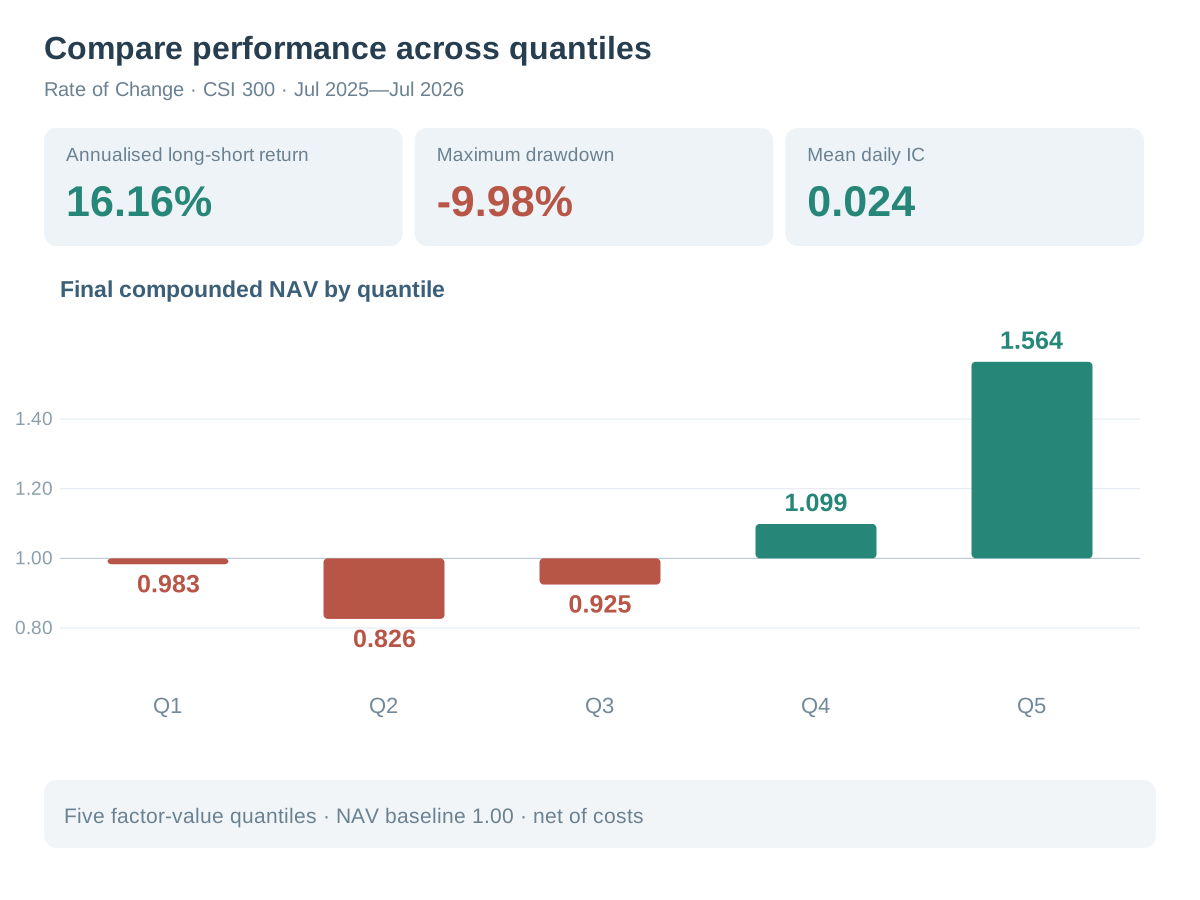
Single-factor evaluation
IC, Rank IC, ICIR, quantile returns and long-short NAV, net of fees and slippage.
Signal synthesis
Combine multiple factors into one signal, connecting factor research with portfolio backtesting.
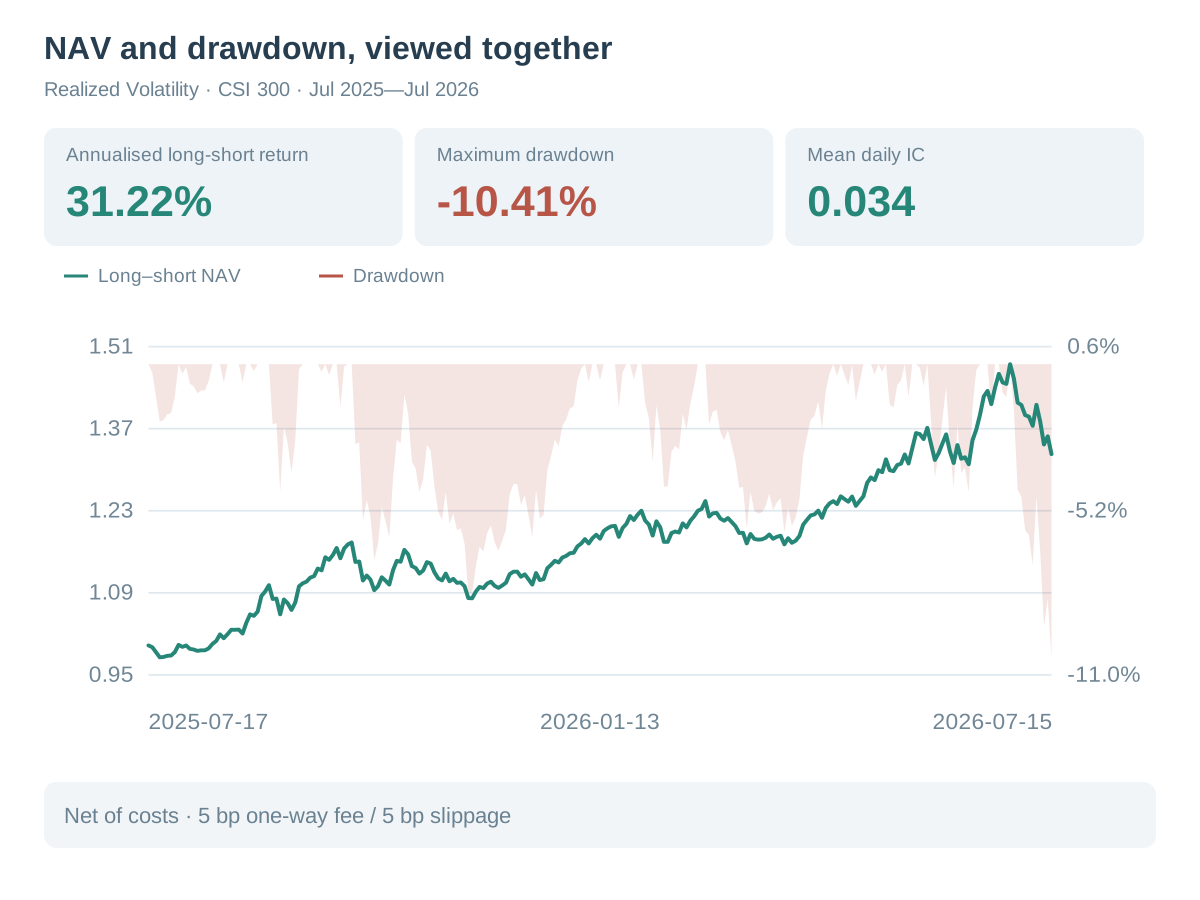
Backtesting
Turn signals into positions: Top K long, quantile long-short or custom weights, with every cost visible.
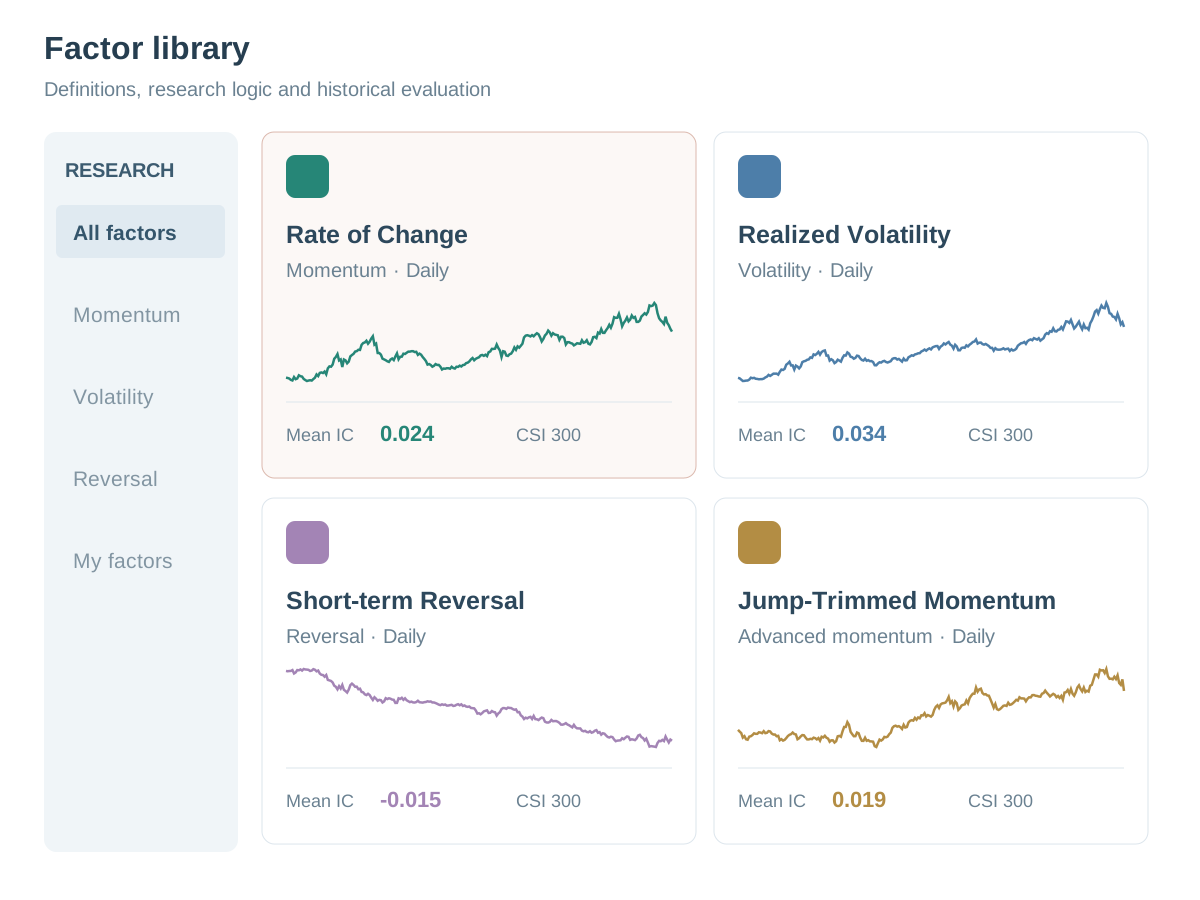
Factor library: from classic factors to your own ideas
- Built-in factors organised by category: volatility, trend, liquidity, reversal, price-volume and momentum, with advanced factors added over time.
- Write your own factors in Python with one input/output format, and use them alongside the built-ins straight away.
- Choose a universe and date range, generate a factor-value package in batch, and use it in every later module.
Single-factor evaluation: is this factor any good?
- IC, Rank IC, ICIR and coverage show a factor's predictive power and stability at a glance.
- 5- or 10-quantile backtests and long-short NAV show whether returns rise steadily across quantiles.
- Costs are deducted using per-side fees and slippage, with turnover reported; external factor files (CSV / Parquet) are supported too.
Signal synthesis: make many factors speak with one voice
- Equal-weight ranks: average each factor's daily cross-sectional rank. No model training, robust and transparent.
- Consistent inputs: combine factors from the same frozen dataset.
- Continue the research: inspect the combined signal, then construct and backtest a portfolio.

Backtesting: turn signals into positions you can test
- Top K equal-weight long, quantile long-short, or custom weights in Python.
- Daily holdings, trades and costs, with NAV and drawdown shown against a benchmark.
- Every backtest records its parameters and data, so results can always be reproduced.
Ordinal: Built for rigorous research
Private by default
A private space for your research.
Point-in-time
Test hypotheses with point-in-time information.
Reproducible
Research records you can revisit.
Multi-market research
Choose your market and research universe.
Want to see what Ordinal can do for your research?
Write to us and we will get back to you soon.
contact@alephedge.com